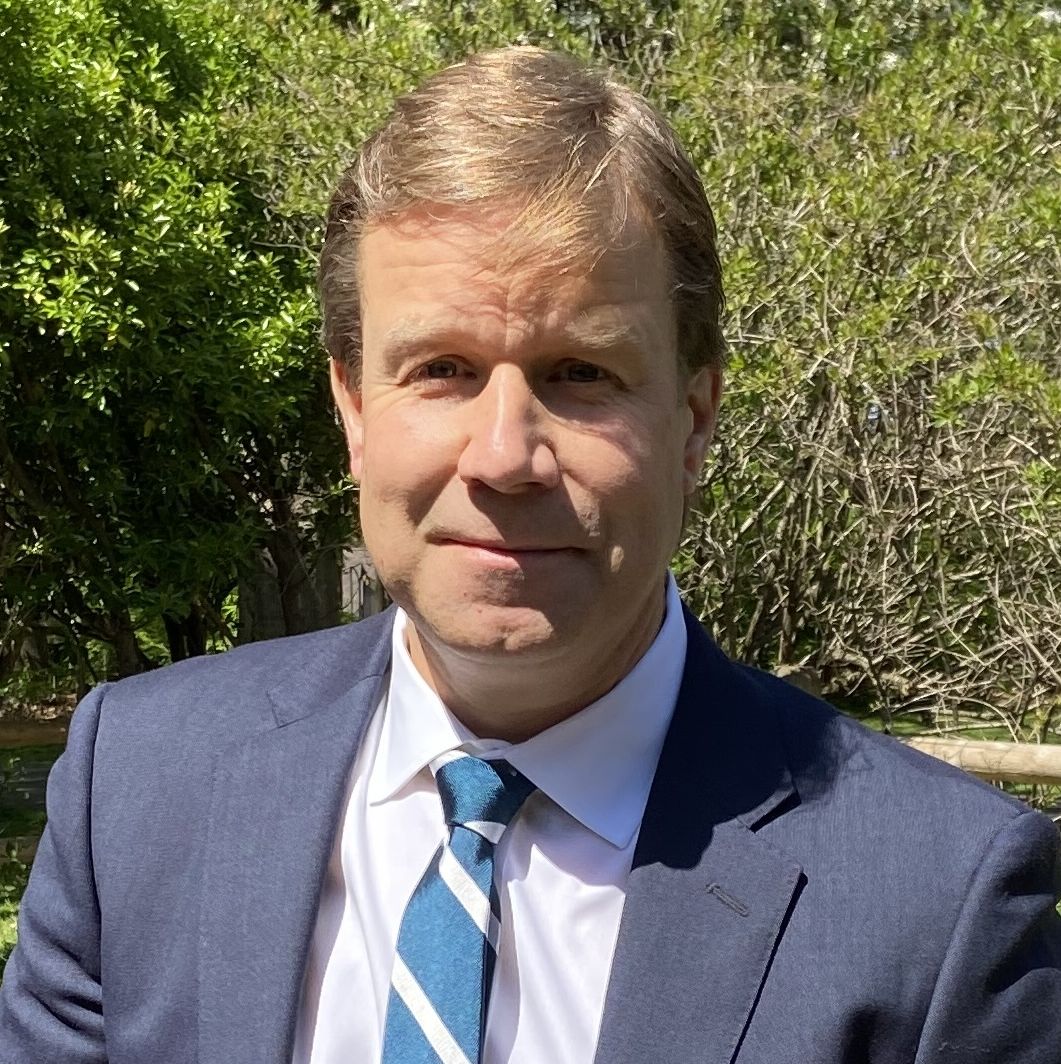
Christopher Kuhn is an Equity Research Analyst at StoneX Group
Christopher Kuhn is an Equity Research Analyst at StoneX Group covering the transportation sector, with a particular focus on trucking, less-than-truckload carriers, intermodal transportation and freight logistics.
He joined The Benchmark Company in 2021 as a Senior Analyst and Managing Director; Benchmark was subsequently acquired by StoneX. Before joining Benchmark, Mr. Kuhn spent 25 years at TIAA Investments, most recently serving as a Sector Portfolio Manager and Analyst covering the U.S. and European aerospace, defense and transportation industries.
He began his career at Goldman Sachs. Mr. Kuhn is a graduate of the Boston University School of Management and Fordham Business School.
TWST: Let’s talk a little bit about AI. There’s been concern among some investors and analysts that AI will eliminate traditional freight brokers, but others argue that these brokers have incredible amounts of data that they can leverage with AI to get even better at what they do.
Talk about that a little bit, maybe the advantages you see for a company like C.H. Robinson, and where is this going.
Mr. Kuhn: AI is a benefit for now.
They’ve been able to use it to improve their productivity, improve their ability to process transactions quicker, find the right lane and the right freight for the right shipment, price it appropriately where they can make money, but they’re not overpricing in a certain lane to where they get priced out.
It is making their employees more efficient, and giving them the ability to concentrate on customer relationships and not some of the manual tasks that take up their time.
As a result, for example, C.H Robinson has improved productivity by around 60% since 2022.
A lot of these transactions are electronic, but it comes from the shipper side. You’re still dealing with a carrier. You’re still dealing with maybe an older driver that uses a flip phone. In shipping, issues and problems come up that AI might not be able to handle at the moment — maybe one day it can. But one of the things that brokers always bring up is you need some sort of personal interaction with the shipper and the carrier.
There’s always something that’s going to go wrong somewhere along the line. The freight might not be there, the shipment might not be there, the driver might have gotten into an accident, the truck might have broken down, all kinds of things. You need to have that personal interaction as well as the AI in the background.
I remember when Uber Freight and all these things were coming out. I thought this is freight and shipping. This is not picking up a person on 42nd and Lex in New York. This is a shipment that has to be there on the dock, that has to have a scheduled pickup, and it’s a lot more complicated than just automating everything.
I think for now, anyway, AI will be a benefit to these companies — to all of the companies: the LTL carriers, the truckload carriers, better network density, better dock efficiency for the LTL carriers, better line-haul efficiency, pickup and delivery.
The big concern would be the slowdown of the data center build because that seems to have been driving the ISM growth at the moment. If that does slow down, you do see the ISM slowing down, which generally is not great for the whole freight industry, specifically the LTLs.
Now, the LTLs, when I ask them, they don’t have that much exposure to data centers, so maybe it’s some peripheral exposure that they’re seeing there. They are seeing a pickup, but it’s not like their volumes are going through the roof right now. But clearly, yes, something to watch is the potential slowdown of the data center build, which could impact the ISM PMI that seems to have been very strong since January.
…
TWST: Let’s talk a little bit about diesel because, as you mentioned, prices are quite high, and we’re probably in for a sustained higher-for-longer diesel environment. Help our readers understand which models are most exposed in the near term, which companies can recover the added costs through fuel surcharges or other mechanisms, and which of the stocks in your coverage area are going to either benefit most from this or deal with it best.
Mr. Kuhn: The thought process is the LTLs are the best positioned here because they benefit the most from higher fuel surcharges. They recover fuel cost inflation a bit faster than TL and the dense network provides an advantage.
Now, clearly with big, huge spikes, there is a fuel surcharge lag. But for most of our coverage — there is a robust fuel surcharge program that generally, ultimately comes out to be neutral.
So fuel is usually a short-term issue in our view, although yes, there is a lag. In addition on the truckload side, they don’t get paid on the empty miles for fuel. So that has an impact if 13%, 14% of your miles are empty miles — your costs are going to go up.
On the flip side of that, that could push out even more capacity. Smaller carriers don’t have the fuel surcharge programs that larger carriers do; they buy on the retail side, not wholesale prices. They are in the spot market, so with spot rates coming down and fuel going up, they start to get turned upside down, and they may not be able to operate profitably. So higher fuel for longer could be another reason more capacity may come out from the small carrier side.
Get the entire interview with Christopher Kuhn is an Equity Research Analyst at StoneX Group, exclusively with the Wall Street Transcript.
BMO Capital is Increasing Return in an Increasing Volatility Stock Market Environment
October 29, 2019
Carpenter Technology Corporation (CRS) Increases Productivity and Synergy in Specialty Metals
April 18, 2013
Interview with the CEO of Itron (NASDAQ:ITRI): Internet of Things (IoT) as a Path to Utility Productivity
February 02, 2022
In an Effort to Save Costs, Companies Outsource to Data Centers
March 25, 2010
Increasing Demand In Metals To See Pickup In Second Half
April 18, 2012